How to compare Model Y L insurance
Australian agreed-value and market-value rules leave different costs out, and new-car replacement expires.

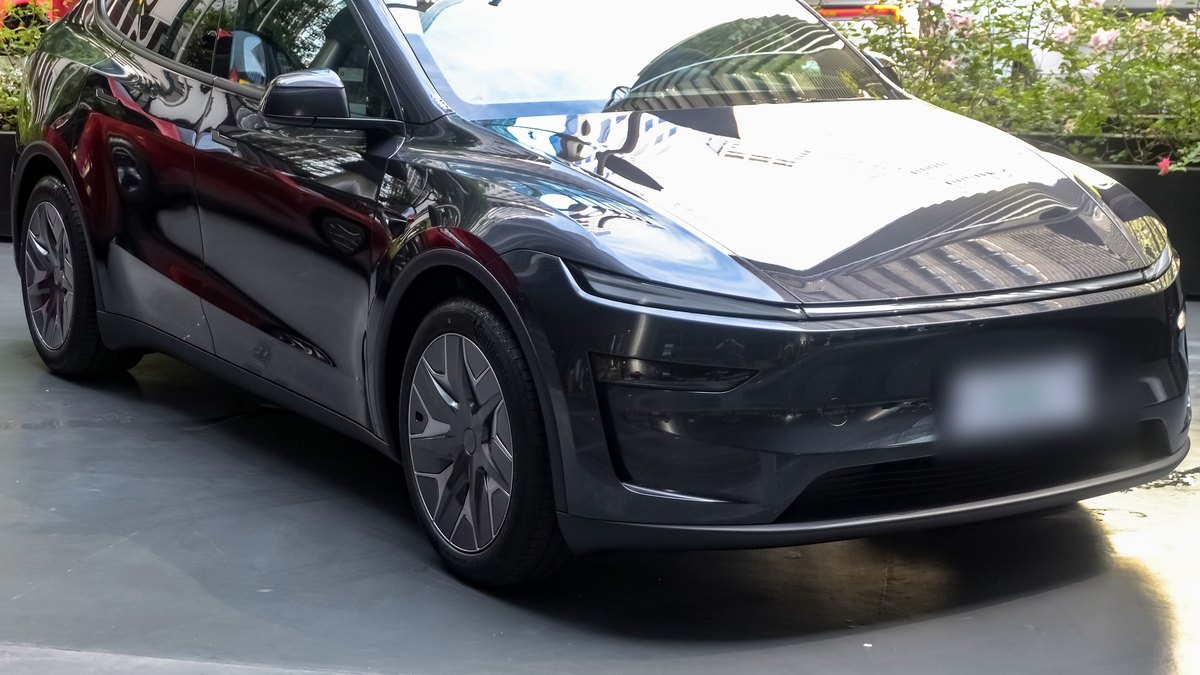 Ethan Llamas / Wikimedia
Key points
- Confirm the quote names the Model Y L before comparing the price.
- Write down the value type, what it includes, and when replacement ends.
- Compare the repairer, the excess and the hire-car limits together.
Ask the insurer to name the Model Y L on the quote before you compare the price. A policy written for electric cars does not show that this car will be accepted.
This is general information about how to read a policy, not advice on your own premium. The Allianz and AAMI examples are current document wording, not a quote for a Model Y L and not a recommendation.
Check the vehicle on the schedule before you pay, along with the drivers, the use and the address. If the quote cannot find the Model Y L, ask for help rather than picking another Model Y.
What the insured value covers
Agreed value is the amount you and the insurer set when the policy starts. Market value is worked out at a total loss, and an excess still comes off. Note the value type, and what the figure includes.
Allianz's new-policy page says Comprehensive cover uses an agreed value, within a range the insurer offers, and Comprehensive Essentials uses market value. On that page, market value leaves out registration, compulsory third party insurance, stamp duty, transfer fees, dealer warranty costs and dealer delivery.
AAMI's comprehensive PDS, prepared on 18 September 2020, is the base document for policies from 15 December 2020. The amount includes fitted accessories and modifications, registration, compulsory third party insurance and GST. Deductions can still apply on a total loss.
AAMI's market-value supplement, for policies bought from 5 August 2021, can replace that amount with market value at the time of the incident. It does not pay stamp duty, transfer fees, dealer warranty costs or dealer delivery.
Wall chargers, paint film and software
List a wall charger and charging cables you own, and ask if their value sits inside the insured amount. Allianz's page covers those accessories if you own them. Custom paint is not its usual cover.
Do not assume a paid software option moves to a replacement car. AAMI's May 2022 supplement covers a film already on the damaged paint, and it pays the repairer's quote rather than re-applying the film.
When new-car replacement ends
| Allianz Comprehensive | AAMI Comprehensive | |
|---|---|---|
| Clock | 2 years from manufacture | Under 2 years from first registration |
| Trigger | Stolen or written off | Accepted as a total loss |
| Car supplied | Same make and model, if available in Australia | Same make, model and series within 90 days |
Allianz's new-policy page gives a choice inside that window: the agreed value, or a replacement of the same make and model where one is available in Australia.
AAMI's PDS adds a buyer test. It includes you, a spouse or partner, a parent, child, grandchild, sibling or grandparent, or a company you direct. The car must have been bought new or as a dealer demonstrator, and the financier must agree in writing.
The PDS then looks for that car within 90 days of the total-loss decision, then a similar car. It pays the initial registration, compulsory third party insurance, delivery and stamp duty.
If AAMI supplies no suitable car, it pays the amount covered less deductions, then cover stops with no premium refund. The replacement benefit is not the balance of a loan. Ask when the benefit ends, and whether a six-seat car counts as similar.
Who chooses the repairer
Allianz Comprehensive lets you choose a repairer. The insurer may get a second quote, and it may pay reasonable repair costs, the agreed value, or replace the car where the conditions are met.
AAMI's PDS says the insurer chooses the repairer. Authorised repairs use new or reusable parts that meet the Australian Design Rules.
Hire car after a claim
For a hire car when you are not at fault, Allianz's page describes a car of a similar size and type for up to 30 days. If that car is not available, it pays $80 a day.
AAMI's included cover is a hire car that meets your transport needs, until the car is returned or the claim is settled. You need the other driver's name, address and registration, and consent before you arrange the car yourself.
Allianz's any-incident option uses that same 30-day car and the same $80 a day. AAMI's optional hire is a similar make or model, at up to $90 a day.
Glass cover and policy exclusions
Allianz removes the excess for one replacement and two repairs a period when only the windscreen, a window or the sunroof is damaged. AAMI's option is one excess-free glass claim a period, and a chip repair does not use it.
Read the exclusions on the same Allianz page. It does not cover mechanical or electrical breakdown, or an unregistered or unroadworthy car. Ridesharing has to be disclosed and accepted.
A battery fire is covered if use and charging followed the maker's specification. Accidental battery damage is not a promise to repair a battery fault.
Which documents apply to the quote
Allianz's policy library puts new policies whose numbers start with AALMV on the set effective from 22 February 2026. An older policy can differ from one sold today.
AAMI's document library lists the PDS, the supplements and the updates that apply together. AAMI's premium guide, for policies from 30 June 2025, is where the excess choices are set, so compare the excess on the certificate.
Keep each quote, its expiry and the schedule with that document set. Before you take the cheapest quote, ask what this policy would pay if the car were written off and new-car replacement did not apply.
Rod Bland is the publisher and editor of Volts & Bots. He lives in Sydney and drives a Model Y L bought in Australia in 2026, with HW4 and FSD (Supervised). More about Rod Bland.